
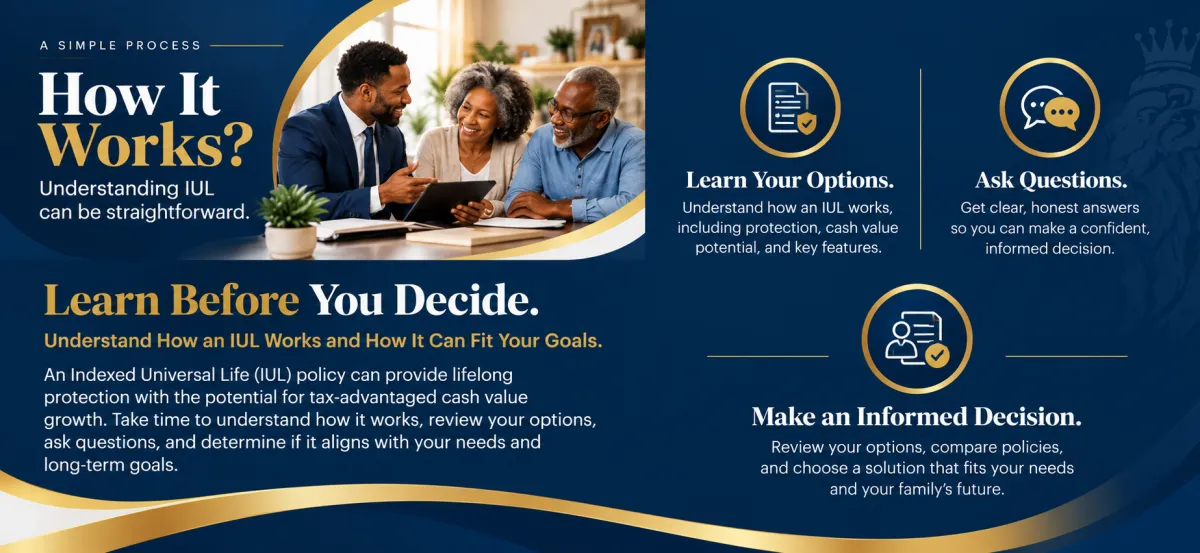
Understanding the basics
What Is Indexed Universal Life Insurance?
Life insurance protection with cash value growth potential.
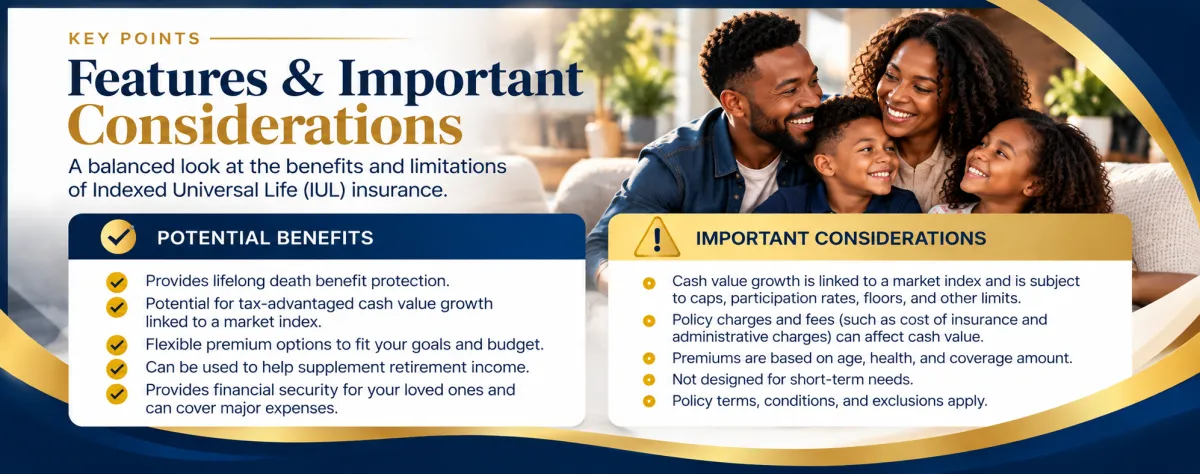
Indexed Universal Life (IUL) is a type of permanent life insurance designed to provide a death benefit while also building cash value over time. Interest credited to the policy’s cash value can be linked to the performance of a market index, subject to the policy’s terms, caps, participation rates, floors, charges, and other limitations.
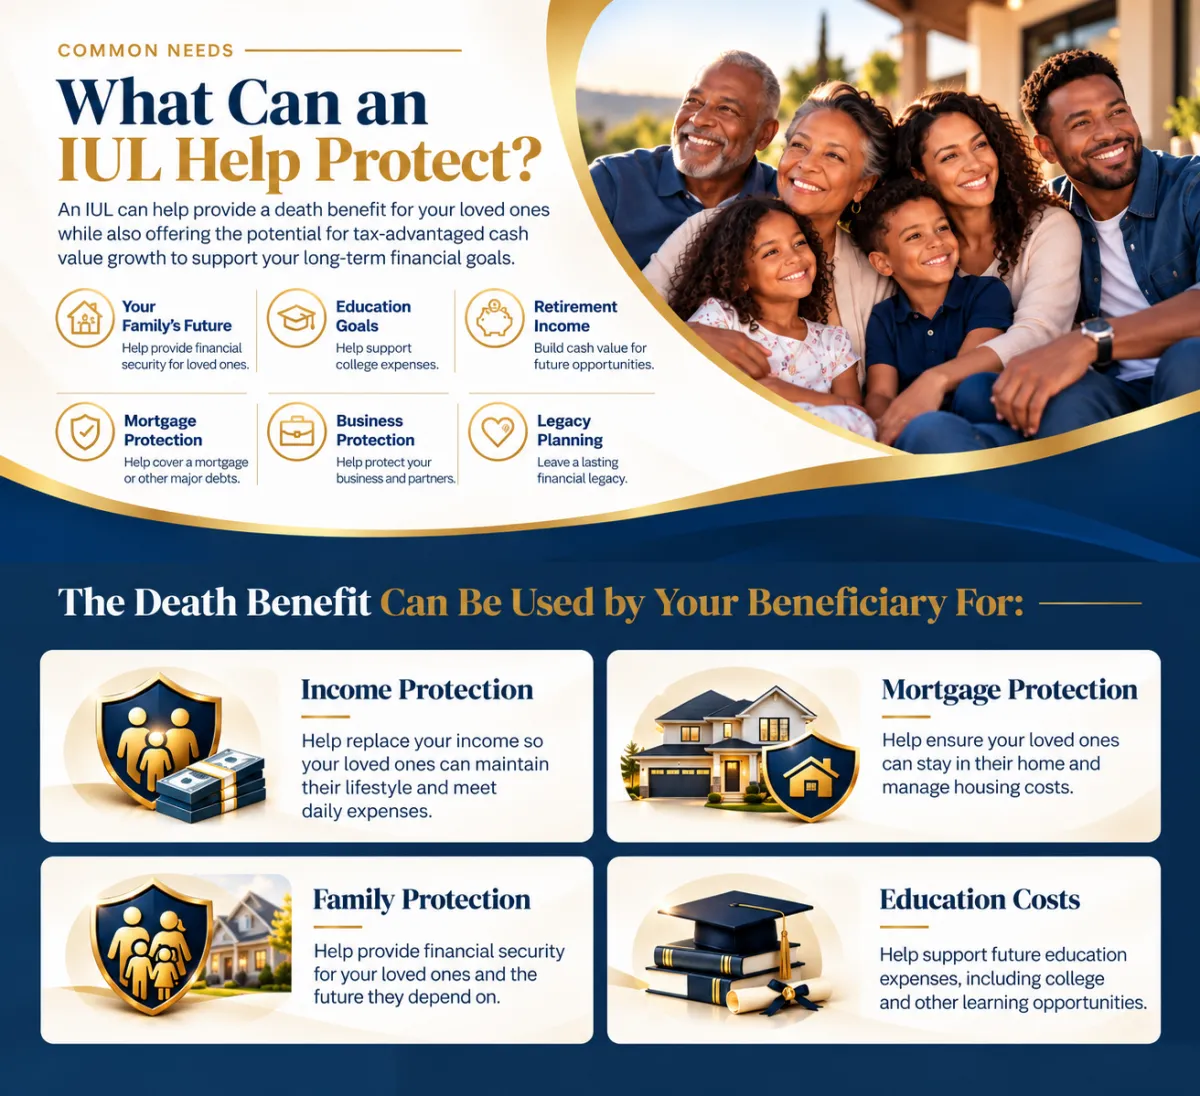
Common Questions
Frequently Asked Questions
Quick answers to help you understand more. I need to talk about my parents tomorrow, so.
What is Indexed Universal Life (IUL) insurance?
Indexed Universal Life is a type of permanent life insurance designed to provide a death benefit while also offering the potential to build cash value. Interest credited to the cash value may be linked to the performance of a market index, subject to the policy’s terms and limitations.
How does an IUL build cash value?
After policy charges and expenses are deducted, a portion of the premium may contribute to cash value. Interest may then be credited based on an index-crediting strategy or other available account options, subject to factors such as caps, participation rates, spreads, and floors.
Is an IUL directly invested in the stock market?
No. An IUL does not directly invest your policy’s cash value in the stocks or securities that make up an index. The index is used as a reference for determining potential interest credits according to the policy’s crediting rules.
What can the death benefit be used for?
Beneficiaries can generally use life insurance proceeds for a variety of needs, including income replacement, mortgage or housing expenses, education costs, debts, final expenses, or other financial priorities.
How are IUL premiums determined?
Premiums and policy funding depend on factors such as age, health, coverage amount, policy design, underwriting, and the selected benefits. Because IUL is flexible-premium insurance, adequate funding and ongoing policy monitoring are important.
Can I access the policy’s cash value?
Generally, yes. Available cash value may be accessed through withdrawals or policy loans, subject to policy provisions. Loans and withdrawals can reduce cash value and the death benefit and may have tax consequences or increase the risk of policy lapse.
What are the key risks or limitations of an IUL?
IUL policies include insurance costs, fees, and other charges, and credited interest is not guaranteed beyond applicable policy guarantees. Caps, participation rates, spreads, and other crediting terms can change, and insufficient funding or poor policy performance can affect cash value and the policy’s ability to remain in force.
Is an IUL appropriate for retirement planning?
An IUL can be used as part of a broader long-term financial strategy because it may accumulate cash value that can potentially be accessed later. However, it is life insurance first, not a retirement account, and suitability depends on your protection needs, funding ability, time horizon, policy performance, and other financial resources.
Contact Us
Michael Cornick Jr.
Real Needs Secured LLC
129 Rockaway Avenue
Valley Stream, NY 11580
Office: 1(646)859-0437
Email: [email protected]
Real Needs Secured LLC
Protect Who Matters Most Today.
Helping individuals and families understand life insurance options and make informed protection decisions.
Explore
Learn Before You Decide
Our Blog
Request Information
© 2026 Real Needs Secured LLC. All rights reserved.
Michael Cornick Jr. is a New York-licensed independent Life, Accident and Health Insurance Agent. Product availability, eligibility, rates and coverage are subject to carrier underwriting and applicable policy terms. Information on this website is provided for general educational purposes only and does not constitute tax, legal or investment advice.